Tesla Q3 2026 Results: Margins Recover as Profits Continue to Decline
Automotive gross margins improved significantly, but operating income fell sharply due to heavy investments in artificial intelligence and new vehicle platforms.
By Christopher Richardson ·
Tesla’s third-quarter operating income fell 56% year over year, a stark drop that underscores the company’s aggressive spending on new technologies despite a recovery in automotive profitability. The electric vehicle maker reported its financial results after the market closed on Tuesday, October 20, providing a detailed look at its performance for the period. While the decline in operating profit was significant, it was accompanied by a notable improvement in core manufacturing margins, signaling a shift in the company's cost structure as it ramps up production of its next-generation vehicles and software services.
Revenue for the quarter remained essentially flat, landing at $28.05 billion. This figure was nearly identical to the $28.1 billion reported in the same period a year ago and aligned closely with Wall Street expectations of $28.06 billion. Non-GAAP earnings per share came in at $0.48, a figure that beat the consensus estimate of $0.45. However, this represented a 4% decrease from the $0.50 reported in the prior year. On a GAAP basis, net income dropped 43% to $787 million, or $0.22 per share, reflecting the broader pressure on the bottom line.
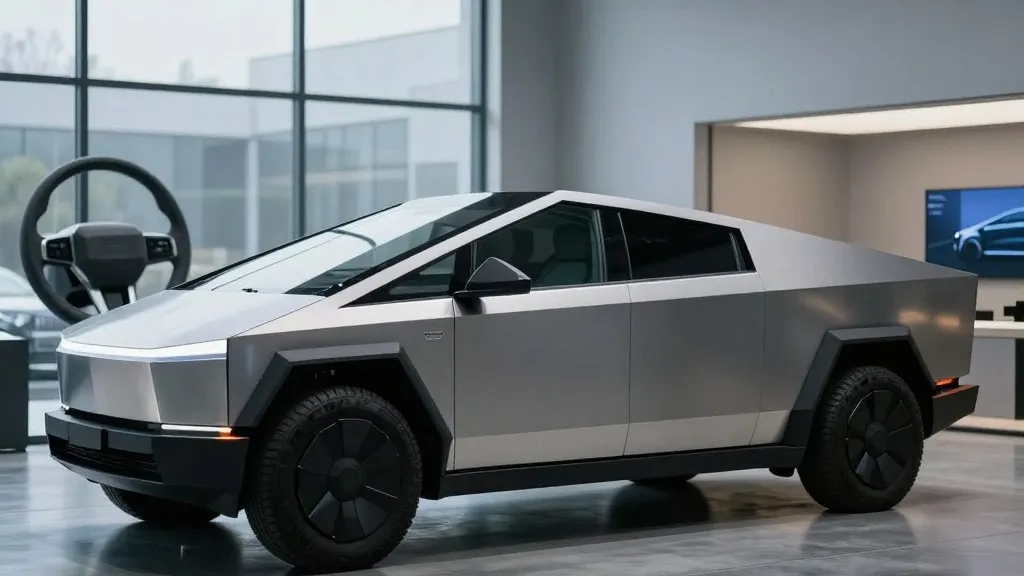
The primary driver of the improved margins was the automotive division. Gross margin excluding regulatory credits rose to 18.1%, up from 16.3% in the previous quarter and 15.4% a year earlier. This improvement was attributed to a better regional and product mix, along with increased revenue from Full Self-Driving subscriptions. In contrast, operating expenses surged 39% to $4.78 billion. Research and development spending jumped 69% to $2.76 billion as the company invested heavily in what it terms Super Intelligence, the Optimus robot, and the Cybercab.
Energy generation and storage was a weak spot for the quarter. Revenue in this segment fell 16% to $2.88 billion, despite a 10% increase in deployments to 13.7 GWh. The decline was partly due to tariff-related customer refunds. However, the segment's gross margin improved dramatically to 33% from 20% in the second quarter. Services and other revenue grew 33% to $4.61 billion, with gross profit hitting a record $734 million driven by charging, insurance, and parts sales.
Management attributed the flat sales volume primarily to battery availability rather than a lack of customer demand. Tesla stated that battery supply continued to be the limiting factor for increasing auto volumes. The company ended the quarter with the largest backlog for passenger vehicles in four years. Deliveries were down 2% year over year, with other models such as the Cybertruck and Model S seeing a 48% decline. Inventory levels decreased to 11 days of supply, down from 15 in the previous quarter.
Capital spending reached $4.73 billion, more than double the amount spent in the same period last year. This heavy investment has led to a year-to-date capex total of $13.01 billion, which is only about half of the more than $25 billion management guided for the full year. To meet that target, Tesla would need to spend roughly $12 billion in the fourth quarter alone. The Q3 letter did not update this guidance, and capital spending actually fell sequentially from the second quarter, raising questions about whether the annual plan is slipping into 2027.
On the technology front, active FSD subscriptions reached 1.74 million, a 67% increase. This count includes upfront purchases, consistent with the definition used in the 2025 CEO pay package. The Robotaxi service also made progress, reaching nearly 2 million cumulative unsupervised miles by the end of the quarter. This milestone was achieved a month after the Cybercab joined the fleet in Austin.
Stock-based compensation was a significant expense, hitting $1.17 billion, up from $663 million a year ago. This figure includes the 2025 CEO pay package. Tesla ended the quarter with $45.4 billion in cash and investments. GAAP net income included a $288 million unrealized gain on bitcoin holdings, which was partly offset by a $142 million unrealized loss on its SpaceX equity investment.
Analysts and investors will look closely at the upcoming earnings call, scheduled for 5:30 p.m. ET, for further clarification on the company's strategy. The full shareholder deck is available on the company’s investor relations site. Management will address the balance between rising investment costs and improving operational margins, as well as the outlook for the fourth quarter and beyond.
Source: Electrek · original report published
More Business · Unethical Practices · Report a business · Got a Story?